
MariBank courts younger customers with child accounts and global stock trading
Sign up now: Get ST's newsletters delivered to your inbox

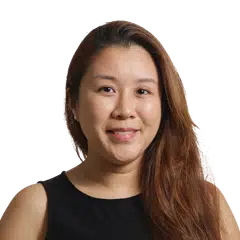
The idea for the child account was mooted by senior management and supported by findings from an internal survey, said MariBank’s head of consumer business Huo Haiyan.
ST PHOTO: AZMI ATHNI
- MariBank is launching child accounts and global stock trading targeting customers aged 16 to 28 to attract digitally savvy youth and promote financial literacy early.
- The bank, whose core user base is in its 20s and 30s, is also expanding its investment options to include US and global equities from early 2027.
- MariBank is expanding beyond Sea's ecosystem, addressing underserved banking needs and aiming to build trust as a primary bank over time.
AI generated
SINGAPORE – Sea-owned MariBank is rolling out child accounts and global stock trading targeted at customers aged 16 to 28, as it looks to capture a growing base of digitally savvy youth.
The idea for the child account was mooted by the digital bank’s senior management and supported by findings from an internal survey, said its head of consumer business Huo Haiyan.
Speaking to The Straits Times at MariBank’s office in Rochester Commons, Huo said several members of the senior management team were heavy users of the bank’s products.
One of them, for instance, wanted a convenient digital method of giving his daughter an allowance, rather than handing her physical cash.
Through an internal study involving parents, the bank found several common concerns, including how to manage children’s transactions and allowances, encourage saving and build financial literacy from a young age.
Targeted for launch in the first quarter of 2027, the child account will let children make their own transactions within parent-set guard rails, with certain transactions, such as adding a debit card to a mobile wallet on a new device, requiring explicit parental approval.
The bank, whose core user base is in its 20s and 30s, is also expanding its investment options to include US and global equities from early 2027.
About 30% of MariBank customers have a Mari Invest account, with one in four Mari Invest customers in their 20s – highlighting growing interest in investing among younger customers.
Among the investment products it offers, the bank said it is seeing a steady upward trend in take-up for its Mari Invest Singapore Equities product. It declined to share specific adoption or customer numbers.
Making investing simple, reliable and rewarding for younger customers who are highly comfortable managing their finances digitally is key, Huo noted.
Growing deposits
The bank is also no longer subject to an individual deposit cap, allowing it to compete more aggressively with traditional lenders for consumer savings.
Mari Savings account holders can now deposit more than $100,000, according to a thread on social media platform Reddit, which Maribank confirmed.
Huo said that many users experienced inconvenience when their incoming transactions or payments could not be completed as their account balance had exceeded the cap. There were a few thousand such transactions being rejected monthly, due to customers hitting their balance caps.
With the cap removed, customers can benefit from MariBank’s high-interest promotions, such as new-user rates and ShopeeVIP bonuses reaching up to 3.08% per annum.
These apply directly to the customer’s full balance and there is no cap on the bonus interest that customers can earn.
Huo said the ShopeeVIP partnership was the main driver of the bank’s deposit growth, with 18% of MariBank users being ShopeeVIP users as well. MariBank’s customer deposits rose from $1.54 billion in 2024 to $2.82 billion by 2025.
Within one month of the ShopeeVIP partnership launch in July, users who claimed the ShopeeVIP bonus interest rates doubled their balances.
Growing outside of Sea’s ecosystem
While Singapore tech giant Sea’s ecosystem will remain one of MariBank’s most important and cost-efficient channels, Huo noted that there will always be “a ceiling and a limit”.
Sea operates three core businesses through its digital entertainment arm Garena, e-commerce platform Shopee, and digital payments and financial services arm Monee, previously known as SeaMoney.
Huo said: “We need to prepare ourselves to reach users outside the ecosystem. We are already trying to scale through other channels such as online marketing and referrals.”
Efforts to leverage other channels have been successful, with more than 50% of MariBank customers now coming from outside Shopee, up from 50% previously.
Entering a mature, heavily banked market where consumers had already established banking relationships also presented a significant challenge.
MariBank therefore focused on addressing the needs of retail consumers and businesses that had not been fully met.
“Our aim is to fill out the white spaces where we see underserved needs,” said Huo.
She added that this includes making overseas money transfers more affordable for businesses and foreigners in Singapore.
“As much as we can, we try to accommodate (these gaps) such that we make the transfer fees affordable, so they can bank with us.”
The bank was also cognisant that building trust with users takes time, particularly as it sought to establish itself as more than a secondary banking option.
“When we launched MariBank, we knew we were going to just be the secondary bank,” said Huo.
She added that the bank eventually began to feel that “there are people who enjoy our services and treat MariBank as their primary bank”. “But it definitely takes time.”
Wearing multiple hats
Scaling up a business from the ground takes time, too.
Huo is no stranger to building businesses, having been part of the founding team behind Shopee before going on to develop products including ShopeePay and SPayLater, a “buy now, pay later” service.
After four years in Shopee, she moved to Sea’s digital payments and financial services arm Monee, where she oversaw 300 product managers across South-east Asia. All this was just six years into her career; she had joined Garena straight out of university in 2014 as a marketing associate.
Reflecting on Shopee’s early days, when the platform was still a largely unfamiliar name in the market, she recalled that customer acquisition was far more challenging than it was when the team launched MariBank in 2023.
At Shopee, she learnt to be prudent with costs and sharpen her people management skills, particularly in identifying the right talent for the organisation.
“One of the biggest takeaways from being in the early Shopee team is how we bring the right people to the organisation so that we don’t dilute the culture, and then we can integrate people with different backgrounds and experiences into the bigger team,” said Huo.
When the opportunity arose to move to MariBank, she embraced it as a natural progression, having already been part of the banking business’ founding team.
Her prior knowledge and experience gave her a strong understanding of the business, while her familiarity with Shopee’s products allowed her to recognise the value she could bring by bridging the two ecosystems and enabling closer collaboration.
She had her fair share of challenges, too. At times, she struggled with self-doubt, particularly when managing people who were more experienced than she was.
“One thing is to accept that there will always be people who are better than you in certain areas. The key is to understand what they are good at and put them in the right roles. At the same time, I had to make sure I wasn’t undermining my own value to the organisation,” said Huo.